Global greenhouse gas emissions continue to rise, driven mainly by increasing emissions in emerging economies and the continued use of fossil fuels. The report “GHG emissions of all world countries – 2025” produced by the European EDGAR database (JRC – European Commission) provides a comparable and consistent snapshot of emissions for all countries, with historical time series updated to 2024.
Why this issue is crucial
Since the beginning of the 21st century, global GHG emissions have followed an upward trend. The immediate effect is an increase in atmospheric concentrations of greenhouse gases, which intensifies the natural greenhouse effect and can have negative impacts on ecosystems, human health, the economy, and social stability.
In parallel, within the framework of the United Nations Framework Convention on Climate Change (UNFCCC), countries develop national emissions inventories and implement mitigation measures. EDGAR supports these processes by providing an independent and internationally comparable estimate, based on IPCC guidelines and updated activity data.
The key figure: a record in 2024
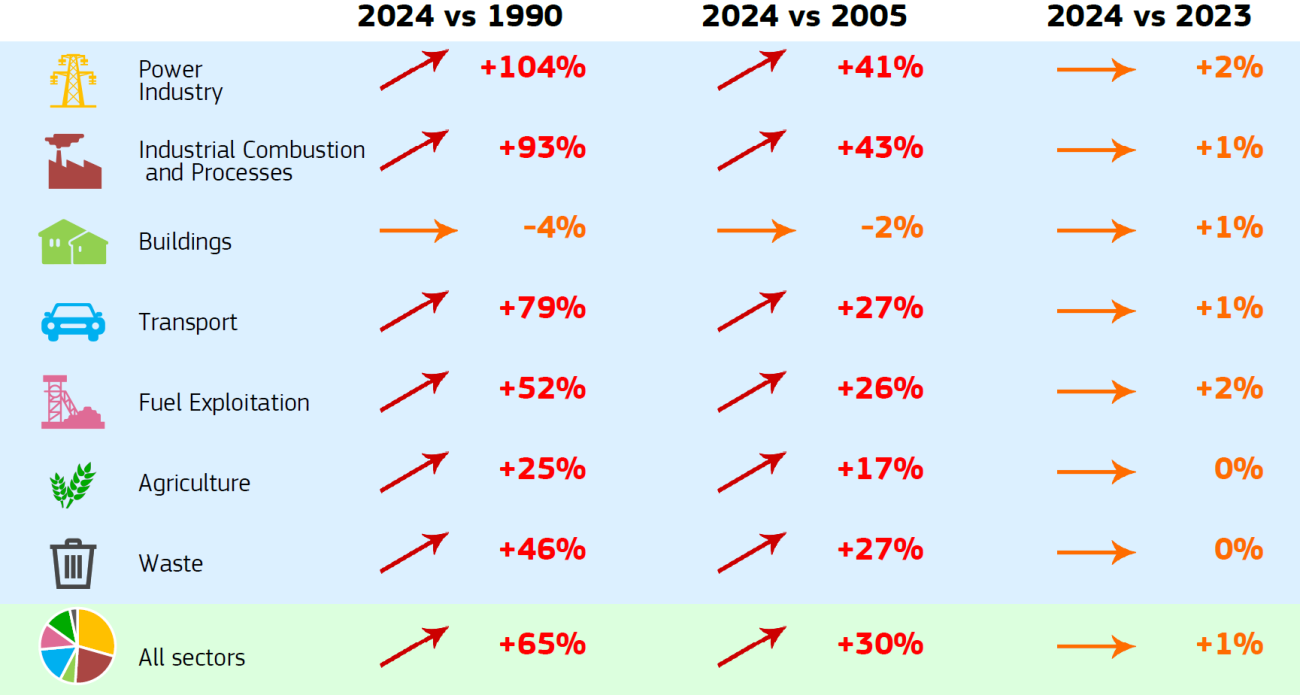
According to the latest estimates, in 2024 global GHG emissions reached 53.2 Gt CO2eq (excluding the LULUCF sector: Land Use, Land Use Change and Forestry). Compared to 2023, this represents an increase of 1.3%, equal to approximately 665 Mt CO2eq.
What “CO2eq” means
“CO2 equivalent” is a unit that allows different gases (CO2, CH4, N2O, F-gases) to be aggregated into a single value, based on their global warming potential (GWP).
The largest emitters in 2024
In 2024, the largest emitters were China, the United States, India, EU27, Russia, and Indonesia. Together, they account for:
- 51.4% of the global population
- 62.5% of global GDP
- 64.2% of global fossil fuel consumption
- 61.8% of global GHG emissions
Among these major emitters, in 2024 China, India, Russia, and Indonesia increased their emissions compared to 2023. Indonesia recorded the highest relative increase (+5.0%), while India registered the largest absolute increase (+164.8 Mt CO2eq).
Which gases matter most
In 2024, the composition of global emissions (again excluding LULUCF) was dominated by fossil CO2, accounting for 74.5% of the total. This was followed by:
- CH4 (methane): 17.9%
- N2O (nitrous oxide): 4.8%
- F-gases: 2.8%
Looking at the long term, fossil CO2 emissions have increased by approximately +74.9% since 1990; CH4 emissions have grown by nearly +30%, N2O by +34%, while F-gases have seen an increase of about +310% over the same period.
The EU27 case: structural decline, but the challenge remains global
For the EU27, GHG emissions (excluding LULUCF) are approximately -35% lower than in 1990, reaching about 3.2 Gt CO2eq in 2024. In 2024, EU27 emissions decreased further by -1.8% (equal to -57.9 Mt CO2eq), and the EU27 share of global emissions fell from 6.1% in 2023 to 5.9% in 2024.
This figure is significant: even with a substantial reduction in Europe, the global trajectory remains upward. In other words, decarbonisation is a system-wide race—what happens in all major economies and along international value chains matters.
What EDGAR is and how to read the data
EDGAR (Emissions Database for Global Atmospheric Research) is a European database that produces independent estimates of greenhouse gas emissions for all countries, using a methodology that is consistent and comparable over time and across geographical areas. The 2025 report update presents time series up to 2024, including emissions from all anthropogenic sectors and the contribution of the LULUCF sector.
The EDGAR portal also provides downloadable files (PDFs and spreadsheets). In particular, data for individual gases (fossil CO2, CH4, N2O, and F-gases), as well as sectoral and country-level details, are available in the Excel file associated with the report.
Practical implications for businesses and policy
- Transition risk: rising global emissions suggest a potential future tightening of policies, carbon pricing mechanisms, and disclosure requirements.
- Value chains: a large share of a company’s climate footprint may lie “upstream” or “downstream” (Scope 3), often in countries where emissions are increasing.
- Mitigation priorities: fossil CO2 remains the dominant component—energy efficiency, electrification, and renewables are key levers, while methane and N2O require targeted sectoral actions (energy, agriculture, waste).
Conclusion
The EDGAR 2025 report confirms that 2024 was another year of growth in global greenhouse gas emissions, despite international climate commitments. Country- and gas-level analysis helps identify where action is most needed and which policies and strategies are most urgent. For those working in corporate sustainability, these figures provide essential context: they define the level of regulatory and market pressure companies are likely to face in the short to medium term.